
|
Check out our new audio content!
Getting your Trinity Audio player ready...
|
Image by dattavispute0 from Pixabay
By Fuquan Bilal
To service a loan that re-performs, you would need a servicer’s assistance. Getting the right servicer for your loan can sometimes be tricky according to your needs and desires. FCI Lender Services, Madison Management and Landhome are a few of the servicers NNG uses. The largest one of these is FCI out of California. It was first founded as foreclosure consultants and today offers an all inclusive outsourcing alternative for loan servicing, collection, and default processing.
Image by Gerd Altmann from Pixabay
The first step to setting a loan up with FCI is completing their setup form. Some of the documents also required are the workout agreement signed by the homeowner along with an ACH form, where applicable. What exactly is the ACH form? It’s a document signed by the homeowner giving permission for funds to be withdrawn from their account on a monthly basis that requires attaching a voided check for account and routing information of the bank account that funds are going to be taken from. In addition to the workout agreement, FCI will also need all information on the borrower and information on the note itself. They also require information from the collateral file such as copies of the note, mortgage, and copies of any assignments proving note belongs to you.
With all the new regulations dictated by Dodd Frank and its enforcing arm, the CFPB, NNG now requires all its note buyers to have a servicer in place before mortgage notes are transferred. In most cases, the buyer will still be able to do the workout, while at the same time remaining compliant with federal procedures.
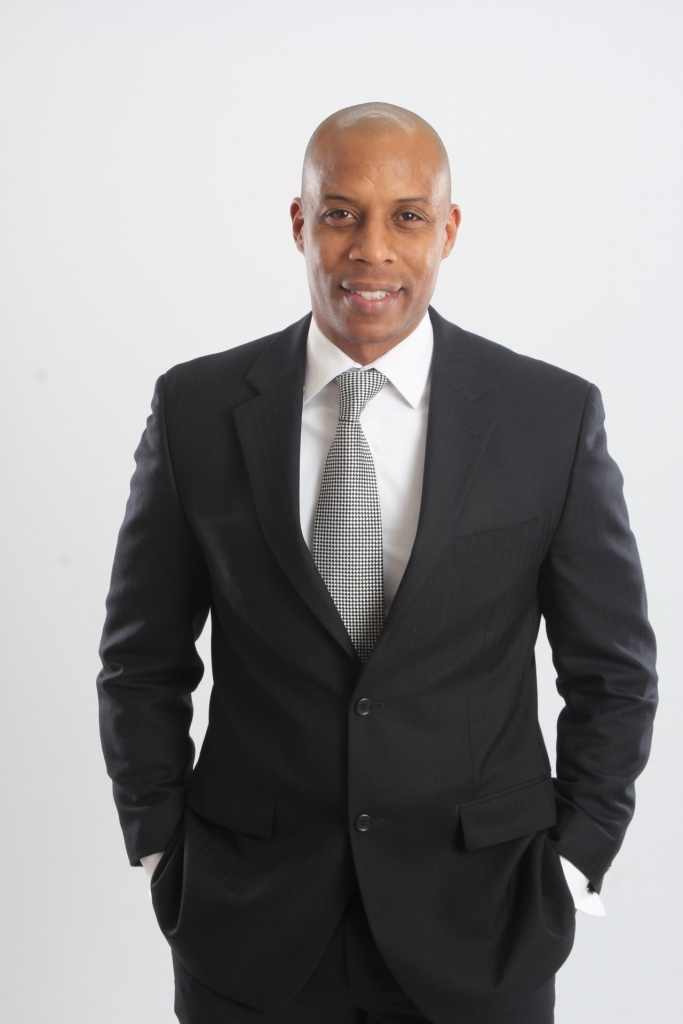
Fuquan Bilal
Fuquan Bilal founded NNG in 2012 with the principal mission of capitalizing on the growing supply of mortgage notes in the interbank marketplace. Mr .Bilal utilizes his 17 years of residential and commercial real estate success to identify real estate opportunities and capitalize on them. To date, he has successfully managed three private mortgage note funds that primarily invest in singlefamily performing and nonperforming mortgage notes. His financial acumen and proprietary set of investment criteria enable him to purchase underperforming real estate assets at a deep discount of face and market values, thereby increasing the value of the assets. This, coupled with his ability to maximize the use of leverage, enables him to build strong, secured portfolios with solid passive income flows.